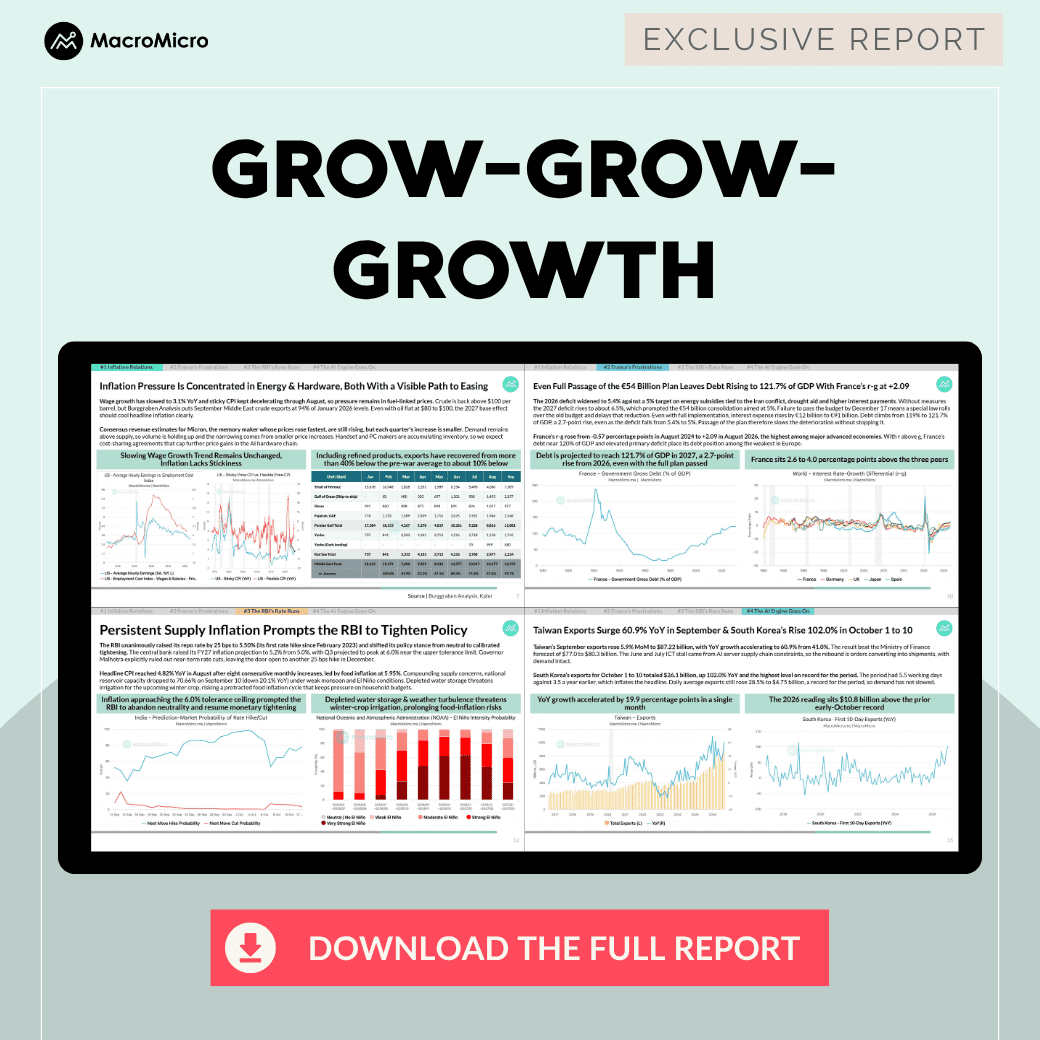
Global equities were mixed last week as higher rates met uneven growth. The US 30-year Treasury yield returned to a 24-year high and the 10-year held near 5.2%, while energy prices stayed elevated on rising risks of tanker attacks in the Strait of Hormuz. Economies with strong growth are absorbing the pressure. US Q2 GDP was revised up to 2.2% annualized, India’s FY27 growth forecast was raised to 7.1%, and AI demand lifted Taiwan’s September exports 60.9% and South Korea’s October 1 to 10 exports 102.0%. France has no such cushion, and borrowing costs above nominal growth are pushing its bond spreads to their widest since the 2011 euro debt crisis. Markets reflected the split, with the Philadelphia Semiconductor Index down 4.30% on concerns over US tech giants’ green-card PERM immigration programs and a union strike at Micron.
This week's WEFC covers four topics: why US growth gives the Fed cover to keep tightening, France’s budget fight where growth offers no relief, the RBI’s return to rate hikes into a margin squeeze, and the AI export boom in Taiwan and South Korea that offsets higher costs.
This Week's WEFC Preview
Growth Gives the Fed Cover: Market Pricing Should Converge Toward Two Hikes and a 2027 Pause
- Officials disagree on the pace, and October hike odds sit just above 20%. Logan sees 50bp or more, Kashkari one more hike this year and one in 2027, and Bowman sees no urgency. The market still prices 3 to 4 quarter-points of hikes, well above the dot plot.
- Inflation pressure is concentrated in energy and hardware, and both can ease. Wage growth has slowed to 3.1% YoY, and the 2027 base effect should cool headline inflation even with oil at $80 to $100. Micron’s estimate increases are shrinking each quarter, and we expect cost-sharing deals to cap AI hardware prices.
- Growth gives the Fed room to hike. Q2 GDP was revised up to 2.2% annualized from 1.5%. We expect two hikes this year and a pause in 2027, and we watch core PCE MoM against 0.2%.
- The bond selloff is a real-yield story. Breakeven inflation barely moved since September, and nominal GDP growth above 6% exceeds our 4.5% to 5% threshold. We favor short-dated Treasuries over long bonds.
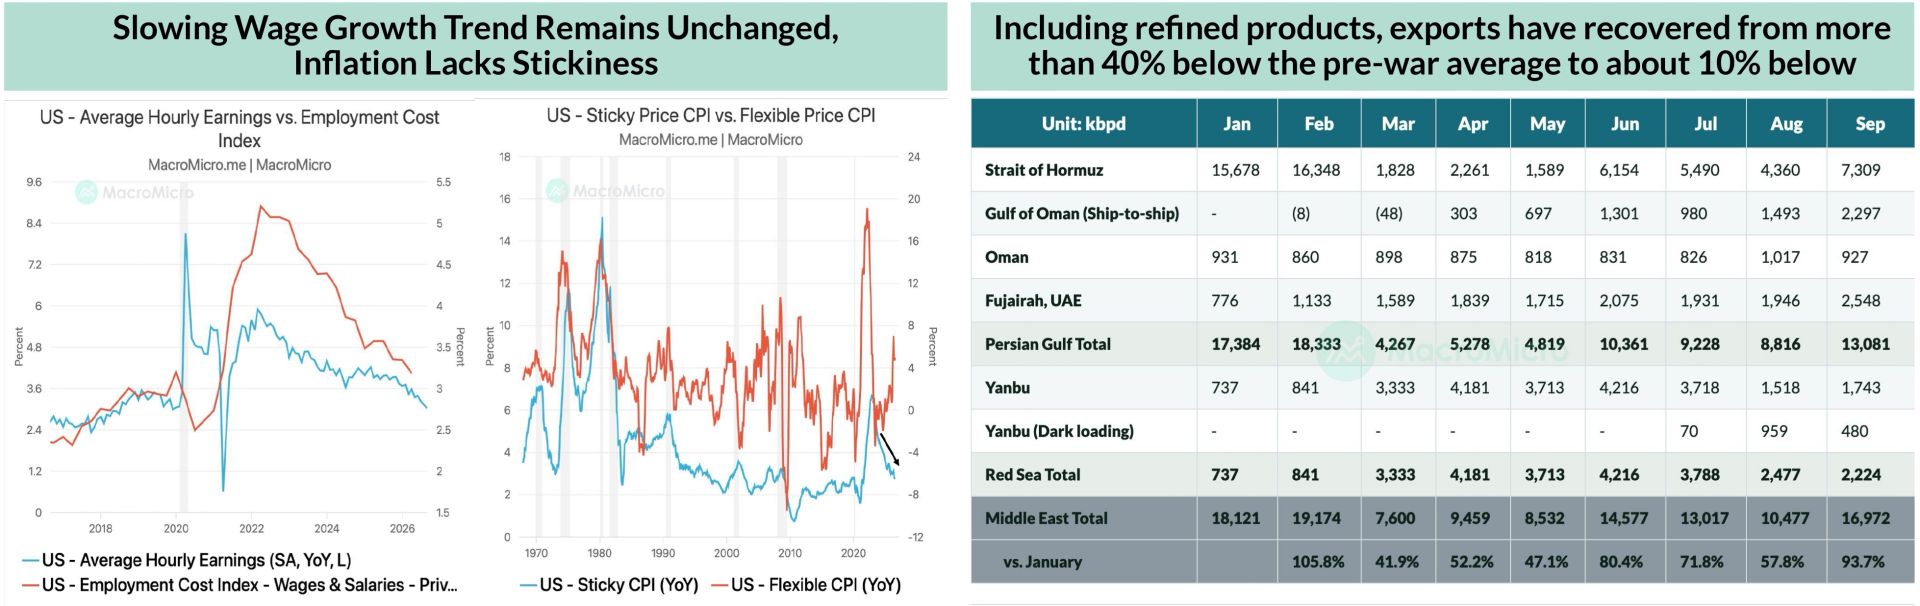
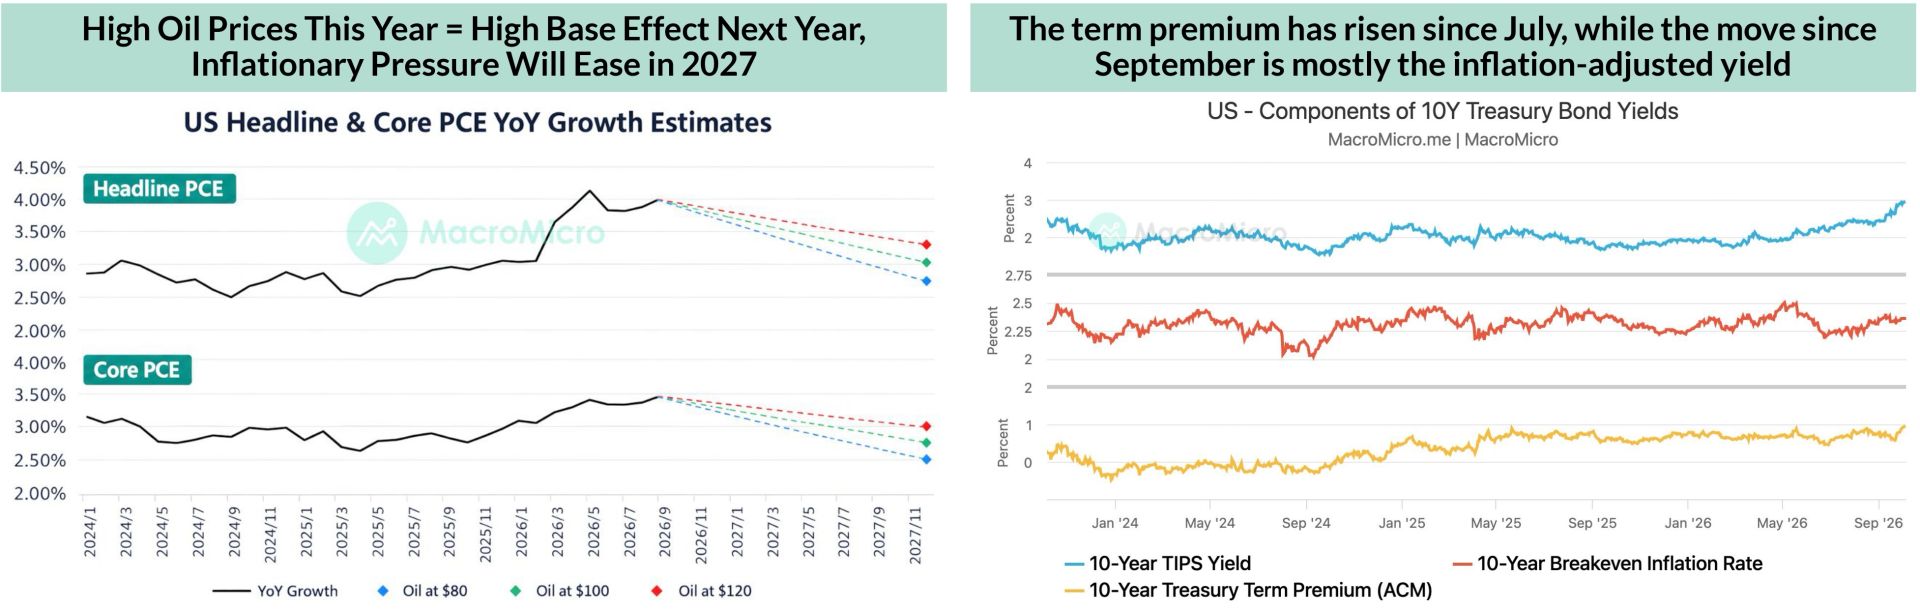
▌Related Charts & Articles: US - FedWatch Interest Rate Projections · US - Components of 10Y Treasury Bond Yields · US - Average Hourly Earnings vs. Employment Cost Index · US - Sticky Price CPI vs. Flexible Price CPI
France’s Fiscal Fix Hits a Political Wall: Spreads Likely Stay Wide Into the Budget Vote
- A fragmented parliament exposes the 2027 budget from both flanks. The Socialists threaten a no-confidence motion unless it is revised, the National Rally opposes the pension freeze, and the Finance Committee rejected the revenue section 31 to 3.
- Even full passage of the €54 billion plan leaves debt rising. Debt climbs from 119% to 121.7% of GDP and interest expense rises €12 billion to €91 billion, even as the deficit falls to 5%.
- Borrowing costs above growth drive the burden. France’s r-g rose from -0.57 to +2.09 percentage points since August 2024, the highest among major advanced economies.
- Spreads are unlikely to narrow before the key dates. The Bund spread spiked toward 159 to 160 bps, past the 152 bps record since 2011. Plenary debate starts October 13, and Moody’s reviews France on October 23.
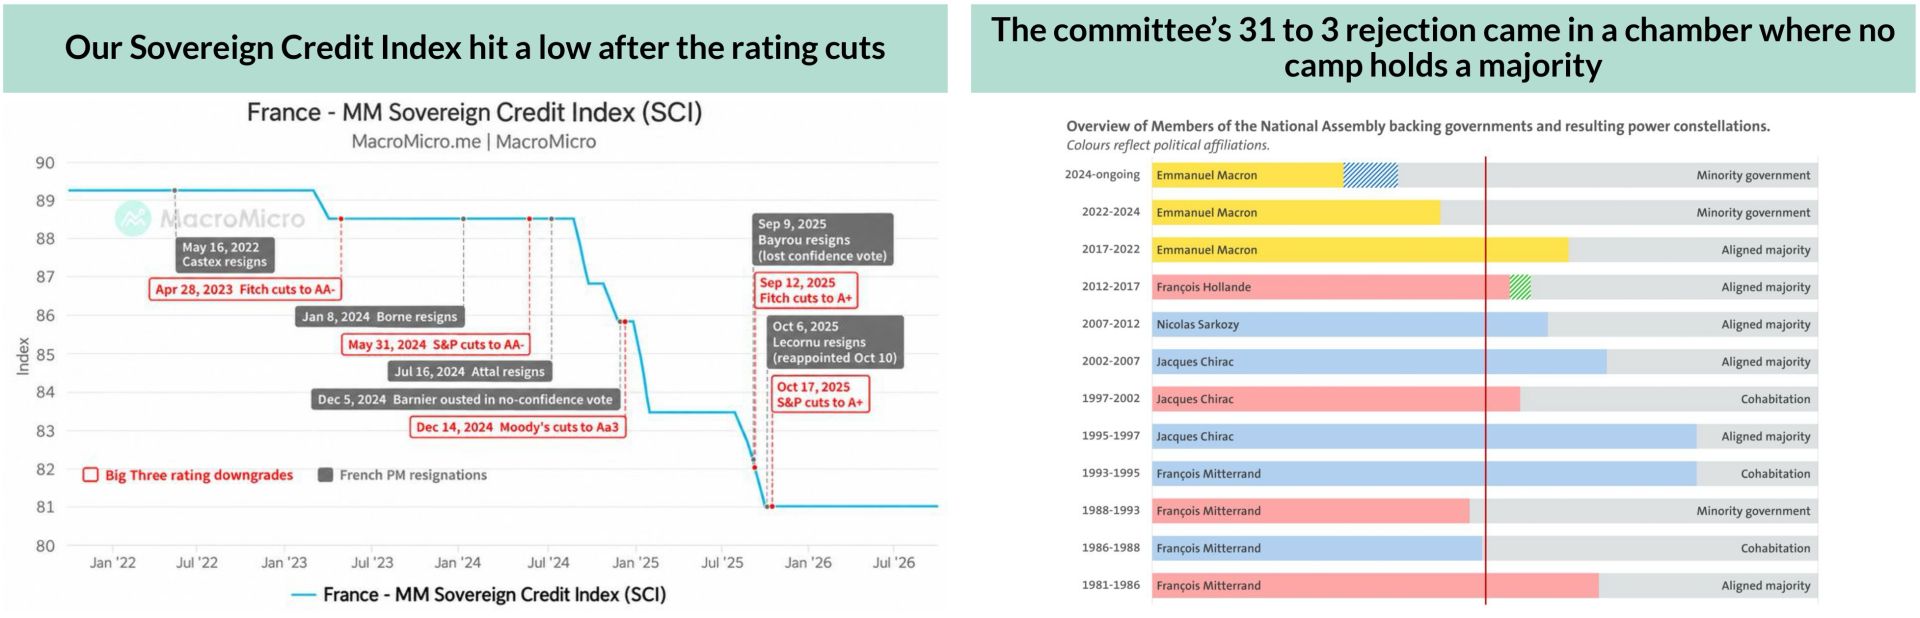
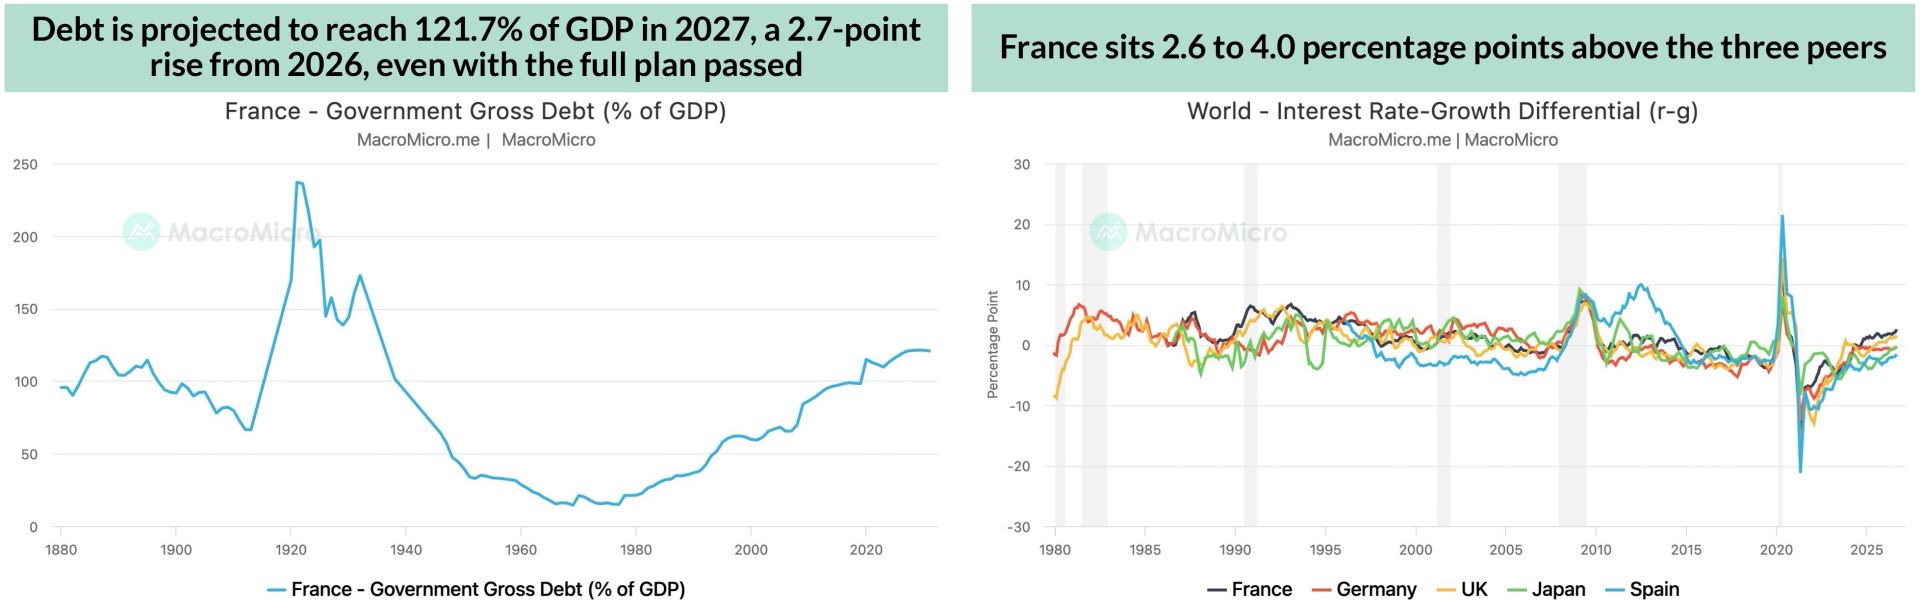
▌Related Charts & Articles: France - MM Sovereign Credit Index (SCI) · France - Government Gross Debt (% of GDP) · World - Interest Rate-Growth Differential (r-g) · Germany/France - 10Y Yield Spread
Subscribe Now to Download the Full Repor
About Weekly Economic and Financial Commentary (WEFC)
The MacroMicro WEFC is published weekly, delivering rigorous analysis and in-depth insights on the most critical market-moving events. Coverage spans equities, foreign exchange, bonds, commodities, global central banks, geopolitics, and the international political economy.
At its core is a concise, roughly 20-page Chart Pack designed to help you grasp market trends at a glance. Subscribe Now» to download the full PDF report, lock in the current offer before prices rise and secure your future upgrade to Max AI with full AI access.
Already a subscriber? Click here to log in.
Full Access to Our Services

Comprehensive data at your service
with key indicators for investment insights

Exclusive flash reports
on key events and data

Create your own charts and analysis
including performance backtesting

Hub of professionals to engage
in meaningful discussions and insights
