Global equities stayed volatile as US–Iran tensions pushed WTI crude back above $100. Last week's US PPI and core CPI both topped expectations, leading us to expect a Fed rate hike, while weaker-than-anticipated Treasury buybacks drove the 10-year yield close to 5%. This week's WEFC focuses on three themes: inflation reignites and a September hike moves into play, structural fiscal expansion meets higher-for-longer yields, and AI's $3.5 trillion off-balance-sheet bet.
This Week's WEFC Preview
Inflation Reignites & a September Hike Moves Into Play
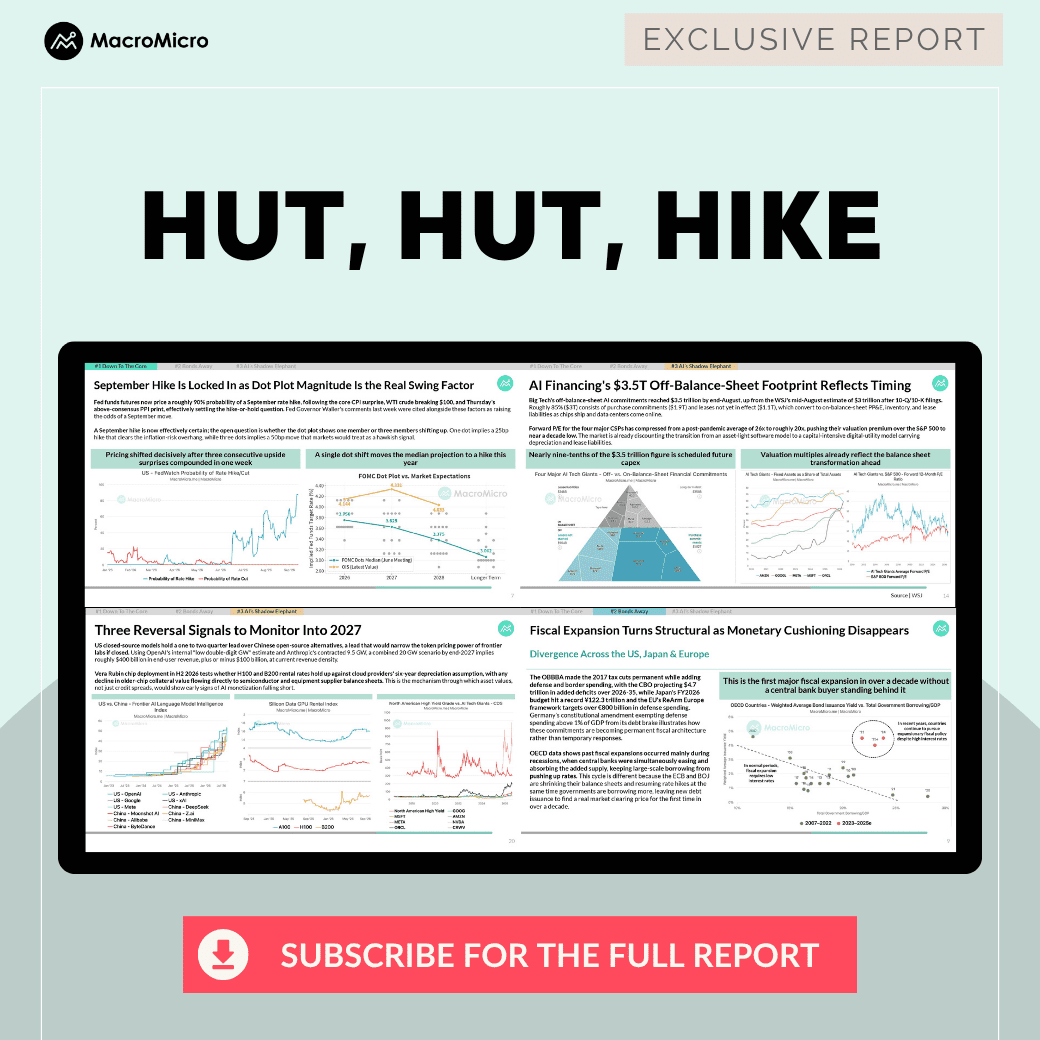
- Markets stayed volatile into the FOMC as yields tested 5% and oil topped $100. Prolonged US–Iran tensions pushed WTI crude back above $100 a barrel. A hotter-than-expected PPI print on Thursday and weak Treasury buybacks drove the 10-year yield close to 5%, before a stable Friday CPI let the three major US indices finish roughly flat; the Philadelphia Semiconductor Index gained 0.76%.
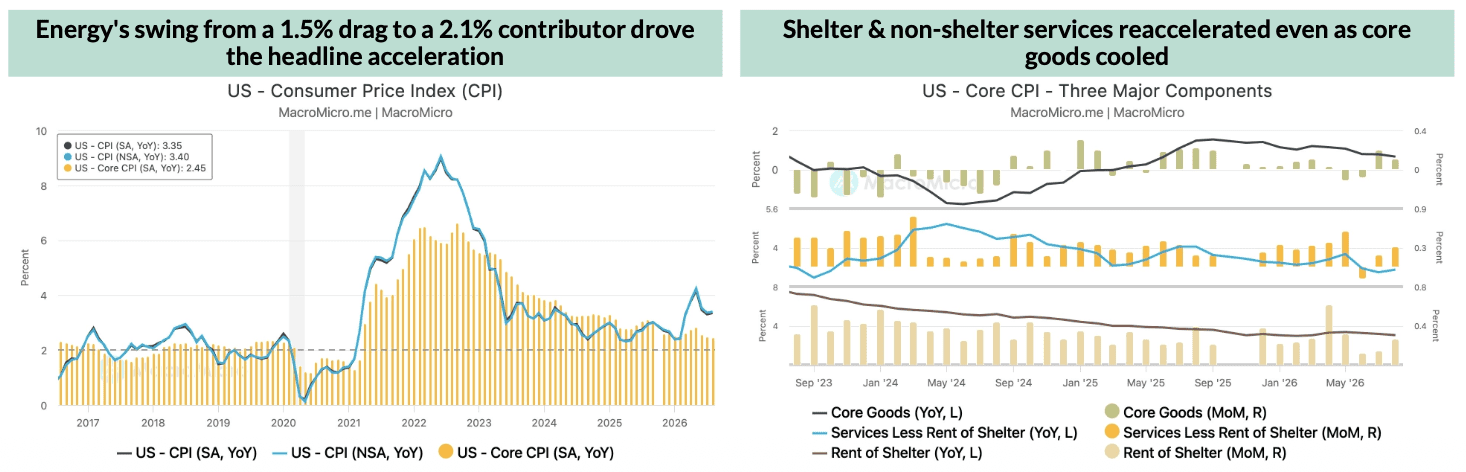
- Headline CPI accelerated to 3.35% as energy swung from drag to driver. August headline CPI rose 3.35% year-on-year, up from 3.30%, with the 0.40% monthly print matching consensus. Energy jumped 2.1% versus a 1.5% July decline, and gasoline alone contributed over a third of the monthly gain.
- Core CPI ran hot beneath a steady headline. Core held at 2.45% year-on-year but the 0.29% monthly gain topped July's 0.22% and crossed the 0.2% threshold. Shelter and non-shelter services both firmed while core goods slowed to 0.1%.
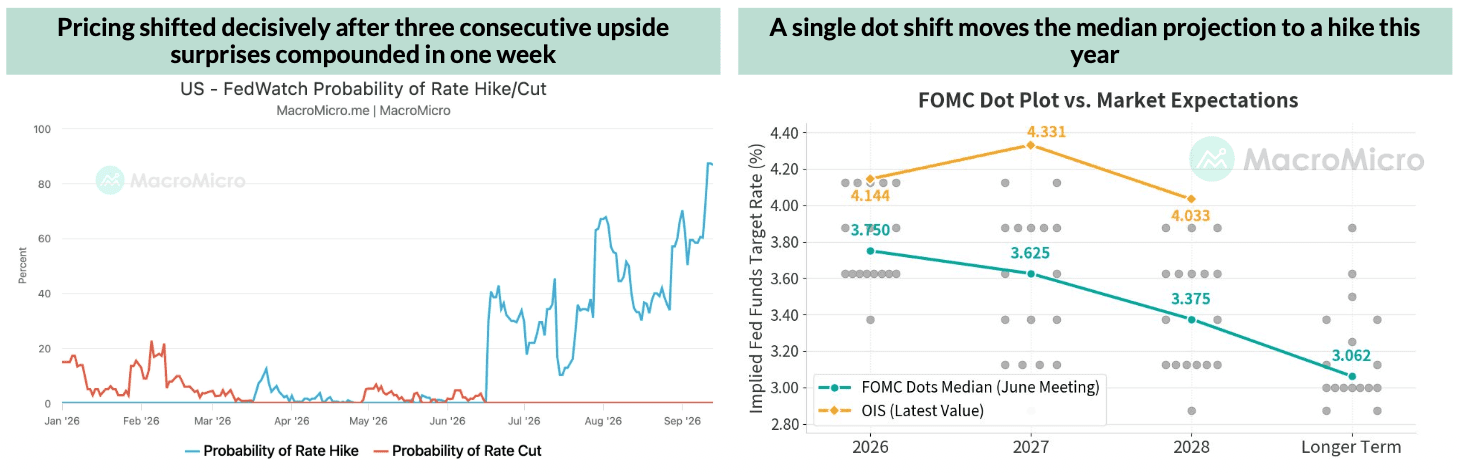
- Fed funds futures now price roughly a 90% chance of a September hike. The core CPI surprise, $100 oil, and the above-consensus PPI print, alongside Waller's comments, effectively settled the hike-or-hold question.
- The dot plot magnitude is now the real swing factor. One dot up implies a 25bp hike that clears the inflation-risk overhang; three dots imply a 50bp move markets would read as hawkish.
▌Related Charts: US - Consumer Price Index (CPI)· US - Core CPI - Three Major Components · US - FedWatch Probability of Rate Hike/Cut · Central Bank Tracker - Fed
The Bond Buyer Is Gone: Structural Fiscal Expansion Meets Higher-for-Longer Yields
- Long-end yields are hitting multi-decade highs simultaneously. The US 10-year climbed above 4.8% and the 30-year reached its highest since June 2007; Germany's 30-year hit 3.79%, its highest since the 2011 debt crisis; Japan's 10-year touched 3% for the first time since 1996 and its 30-year set a record 4.14%.
- Fiscal expansion has turned structural, without a central bank buyer. Developed-economy sovereign debt hit a record $61 trillion in 2025, with net borrowing set to near $4 trillion in 2026. The OBBBA made the 2017 tax cuts permanent (CBO: $4.7T added deficits over 2026–35), Japan's FY2026 budget hit ¥122.3T, and the EU's ReArm framework targets over €800B. Unlike past expansions during recessions, the ECB and BOJ are now shrinking balance sheets and hiking.
- The ECB and BOJ resumed hikes, ending the global cutting cycle early. The ECB lifted its deposit rate 25bp to 2.50% after a Rhine drought and $100 oil pushed eurozone HICP to 3.3%. The BOJ is expected to hike 25bp to 1.25%, with Japan's MOF reporting foreign-securities sales roughly matching intervention scale — Treasury sales funding yen support.
Subscribe Now to Download the Full Report
About Weekly Economic and Financial Commentary (WEFC)
The MacroMicro WEFC is published weekly, delivering rigorous analysis and in-depth insights on the most critical market-moving events. Coverage spans equities, foreign exchange, bonds, commodities, global central banks, geopolitics, and the international political economy.
At its core is a concise, roughly 20-page Chart Pack designed to help you grasp market trends at a glance. Subscribe Now » to download the full PDF report, lock in the current offer before prices rise and secure your future upgrade to Max AI with full AI access.
Already a subscriber? Click here to log in.
Full Access to Our Services

Comprehensive data at your service
with key indicators for investment insights

Exclusive flash reports
on key events and data

Create your own charts and analysis
including performance backtesting

Hub of professionals to engage
in meaningful discussions and insights
 Get answers from MM AI.
-
What factors caused market volatility and increased US Treasury yields?
💡Market volatility and increased US Treasury yields were primarily caused by prolonged US-Iran tensions pushing WTI crude above $100 a barrel, a hotter-than-expected Producer Price Index (PPI) print, and weaker-than-anticipated Treasury buybacks that drove the 10-year yield close to 5%. Despite a stable Friday CPI, these factors created significant market fluctuations, influencing global equities and bond markets.
-
What is the likelihood of a Fed rate hike in September?
💡The likelihood of a Fed rate hike in September is approximately 90%, as priced by Fed funds futures. This high probability stems from the surprise increase in core CPI, WTI crude oil topping $100 per barrel, the above-consensus PPI print, and recent comments from Waller, which collectively settled the debate regarding a hike or hold decision.
-
How did global long-end yields reach multi-decade highs?
💡Global long-end yields reached multi-decade highs due to a combination of factors, including the US 10-year climbing above 4.8% and its 30-year reaching its highest since June 2007, Germany's 30-year hitting 3.79% (its highest since the 2011 debt crisis), and Japan's 10-year touching 3% for the first time since 1996 with its 30-year setting a record 4.14%. These increases reflect a broader trend of structural fiscal expansion without central bank buyers.
-
Why did the ECB and BOJ resume interest rate hikes?
💡The ECB and BOJ resumed interest rate hikes due to persistent inflationary pressures and a shift away from accommodative monetary policies. The ECB lifted its deposit rate by 25bp to 2.50% following a Rhine drought and $100 oil pushing eurozone HICP to 3.3%, while the BOJ is expected to hike 25bp to 1.25% as it normalizes policy amidst reports of foreign-securities sales to support the yen.
-
How can AI productivity help stabilize debt-to-GDP ratios?
💡AI productivity can help stabilize debt-to-GDP ratios by driving economic growth. The US needs an additional 1.1 percentage points of growth and Germany needs 0.8 percentage points to stabilize their respective ratios, both of which are considered reachable through widespread AI diffusion. However, AI alone may not fully close the gap for countries like Japan (+1.6pp), France (+2.0pp), and the UK (+2.3pp).
-
How did strategic equity stakes affect Big Tech's Q2 profits?
💡Strategic equity stakes significantly affected Big Tech's Q2 profits, converting $160 billion of profit into non-operating gains. This amount, representing 45% of the combined pre-tax profit increase for Google, Amazon, Meta, Microsoft, and Nvidia (which rose from ~$100 billion in 2024 to nearly $350 billion in Q2 2026), resulted from revaluations of their stakes in companies like OpenAI, Anthropic, and SpaceX, boosting 'Other Income'.
-
What are the key tail risks in AI financing arrangements?
💡The key tail risks in AI financing arrangements are concentrated behind 10% of the total commitments and involve Special Purpose Vehicles (SPVs) and residual-value guarantees. Examples include Broadcom extending up to $29 billion in lease guarantees, Nvidia backing a Valor-led SPV holding $5.4 billion in GB200 chips for xAI, and Meta providing guarantees running as long as 16 years. These arrangements concentrate exposure, with CDS on AI infrastructure names already pricing this risk ahead of equities.
AI Supply Chain Hub + Live Outlook Track the $1T AI megatrends and the entire supply chain—all in one plan. → Claim It Before Sep 30