What You Should Know
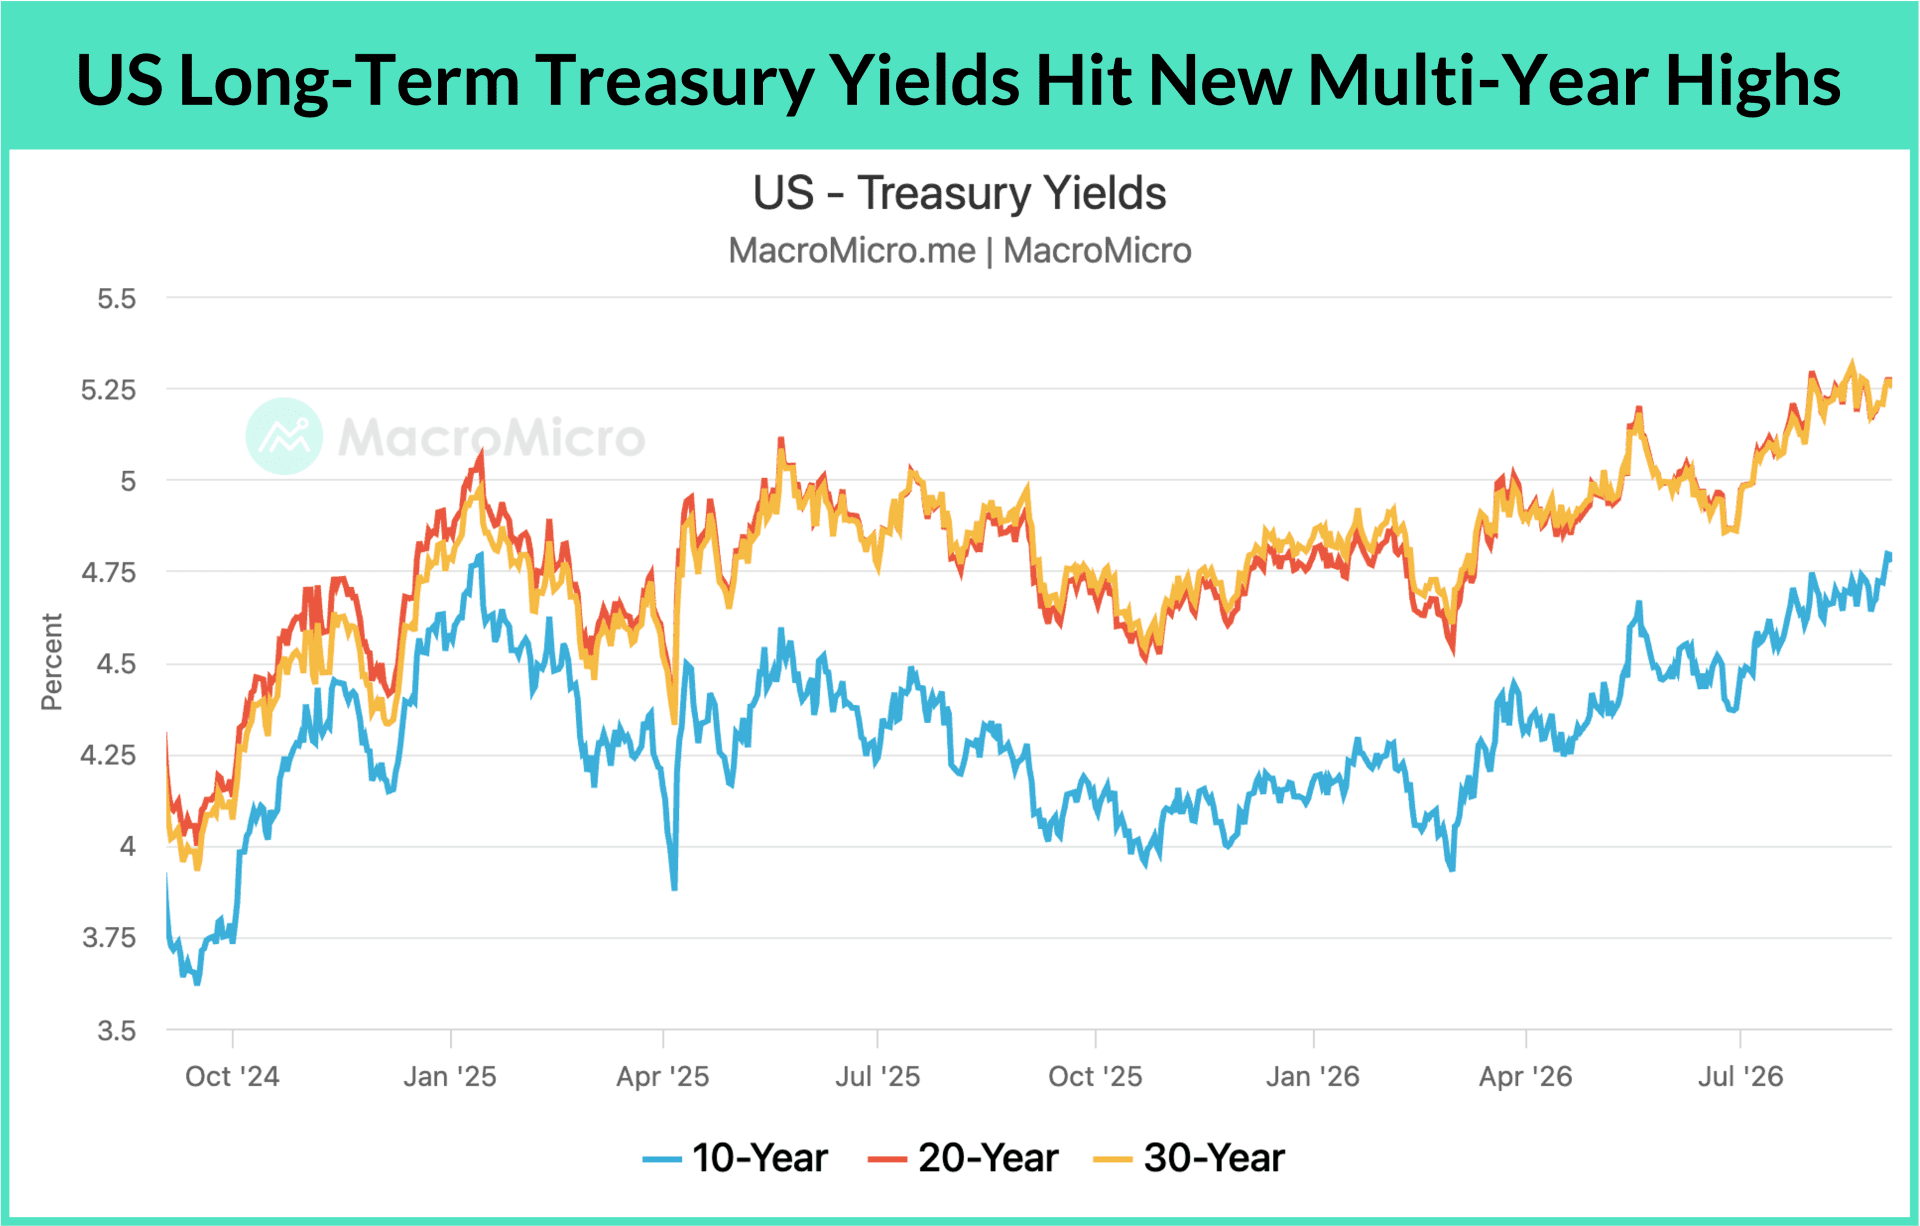
In recent months, long-dated US Treasuries appear to be increasingly at risk of losing control. Even after the Treasury Department announced plans to expand the scale of long-dated Treasury buybacks, 10-year and 30-year Treasury yields have continued to climb, breaking through key levels of 4.8% and 5.2%, respectively. The 10-year Treasury yield this week also reached a new high since 2025.
Looking at the components of Treasury yields, the key driver behind the recent rise in rates has been the continued increase in the Term Premium, reflecting investors' demand for greater risk compensation for holding long-dated bonds. On the one hand, this reflects a repricing of long-term risks, including unclear Federal Reserve policy signals and geopolitical conflicts that remain unresolved. On the other hand, it also reflects growing concerns over the sustainability of US fiscal policy and debt.
Could these pressures push the debt burden into a vicious upward spiral? We want to return to the most fundamental formula to help you fully assess the current situation:
Change in Debt Ratio = Fiscal Deficit Ratio + (r - g) × Current Debt Ratio (Debt ratio and fiscal deficit ratio are both expressed as a percentage of GDP)
Here, r is the financing cost, while g is nominal economic growth. In other words, there are essentially three ways to bring down the debt ratio: reduce the fiscal deficit, lower interest rates, and increase economic growth. How is the US progressing along these three paths? Is the situation gradually improving, or is it moving in the opposite direction? In this article, we will examine each of these paths in detail.
Key Takeaways
- Fiscal deficit: Tariffs reduced the fiscal deficit in fiscal 2025, but the impact remains small relative to the overall deficit. There is currently no credible path toward sustained deficit reduction.
- Borrowing costs: Short-term rates remain well anchored amid stable demand, while future supply and demand are likely to gradually shift toward short-term Treasuries. During this transition, long-term rates will rely on regulatory adjustments and liquidity tools to strengthen market capacity to absorb Treasuries and stabilize yields.
- Economic growth: AI-driven productivity growth is the ultimate solution. It can increase tax revenue and improve the deficit, while also improving the debt ratio by expanding the denominator.
- Asset allocation: As long as economic growth continues and the economy remains in expansion, equities over bonds remains the overarching principle. In the bond market, however, investors should note that long-dated Treasuries are likely to remain more volatile while the maturity structure of US debt remains overly concentrated at the long end. Therefore, for investors who still need bond exposure to reduce portfolio volatility, short-term Treasuries are likely to be the better choice.
I. Fiscal Deficit: No Credible Path Toward Deficit Reduction Yet
Starting with the fiscal deficit, the US fiscal deficit fell to $1.78 trillion in fiscal 2025, from $1.83 trillion previously. The decline was mainly driven by the Trump administration's sharp increase in tariffs. The overall effective tariff rate rose from around 2.4% at the beginning of 2025 to approximately 11% today, pushing tariff revenue to a record $195 billion in fiscal 2025, up from $118 billion previously, an increase of more than 50%. As a result, the fiscal deficit as a share of GDP improved to 5.9%, from 6.3%.
Nevertheless, tariff revenue remains small relative to the current fiscal deficit. More importantly, the Trump administration has clearly shown little intention of meaningfully reducing government spending, making it difficult for tariff revenue alone to generate a sustained narrowing of the deficit. In fact, the cumulative fiscal deficit through July of fiscal 2026 was already close to $1.8 trillion, exceeding the total for the previous fiscal year. Meanwhile, median forecasts from the Congressional Budget Office (CBO), Office of Management and Budget (OMB), and primary dealers indicate that most institutions expect the US fiscal deficit to continue expanding over the next three years and exceed $2 trillion. According to IMF forecasts, the US fiscal deficit is expected to remain around 7% of GDP through 2030.
Therefore, tariff revenue can help improve the fiscal position in the short term, but tariffs alone are unlikely to reverse the structural deficit problem. At this stage, the first path, "reducing the fiscal deficit," remains extremely difficult. This means that if the US is to ease its debt burden, the answer must instead come from...
Already a subscriber? Click here to log in.
Full Access to Our Services

Comprehensive data at your service
with key indicators for investment insights

Exclusive flash reports
on key events and data

Create your own charts and analysis
including performance backtesting

Hub of professionals to engage
in meaningful discussions and insights
 Get answers from MM AI.
-
What are the three primary ways to reduce the US national debt ratio?
💡The three primary ways to reduce the US national debt ratio, according to the fundamental formula Change in Debt Ratio = Fiscal Deficit Ratio + (r - g) × Current Debt Ratio, are to reduce the fiscal deficit, lower interest rates (financing cost 'r'), and increase economic growth (nominal economic growth 'g'). These factors directly influence the debt ratio expressed as a percentage of GDP.
-
Why have short-term US Treasury rates remained stable despite rising long-term yields?
💡Short-term US Treasury rates have remained stable, with the 3-month Treasury bill yield at 3.9%, primarily due to a lack of need for aggressive Federal Reserve rate hikes as core inflation remains controlled and wage growth slows. Additionally, demand for short-term Treasury bills remains stable, supported by large money market funds approaching $8 trillion, and the Federal Reserve's strategy of reinvesting maturing MBS into short-term Treasury bills.
-
How might stablecoin market capitalization impact demand for short-term US Treasuries by 2028?
💡Stablecoin market capitalization could significantly impact demand for short-term US Treasuries by 2028, with estimates suggesting an eightfold growth to $2 trillion. This expansion would imply their short-term Treasury reserves could increase from approximately $120 billion to $1 trillion, nearing the holdings of Japan, the largest foreign holder of US Treasuries at about $1.1 trillion, thereby increasing overall demand for short-term government debt.
-
What changes is the US Treasury Department making to its issuance strategy for long-dated bonds?
💡The US Treasury Department is adjusting its issuance strategy by potentially issuing more short-term debt and reducing long-term issuance, evident in a shift in language in its August quarterly refunding announcement. This change from assessing the possibility of 'increases' to 'changes' for future coupon-bearing Treasury auctions suggests an intention to modify the maturity structure of Treasury issuance to ease the term premium demanded by investors for holding long-dated bonds.
-
What is the SEC's central clearing rule for US Treasury transactions, and why is it important?
💡The SEC's central clearing rule for US Treasury transactions mandates that eligible transactions gradually transition to central clearing, with compliance deadlines by the end of 2026 for cash transactions and June 30, 2027, for repo transactions. This rule is important because central clearing improves netting efficiency, reducing the balance sheet space and capital required for financial institutions, thereby increasing their capacity to absorb US Treasuries.
-
How can increased labor productivity through AI improve the US fiscal deficit and debt ratio?
💡Increased labor productivity through AI can improve the US fiscal deficit and debt ratio by expanding the denominator (GDP) in the debt-to-GDP ratio without requiring fiscal austerity and by directly expanding the tax base. The Congressional Budget Office estimates that every 1 percentage point increase in annual labor productivity growth could reduce the cumulative deficit by approximately $3.17 trillion over 10 years, fostering a positive fiscal cycle.
-
What was the impact of the internet boom on US productivity growth and the debt-to-GDP ratio?
💡The internet boom of the 1990s significantly impacted US productivity growth, which at one point approached 4% on an annualized basis, while nominal growth reached 7%. This surge directly contributed to four consecutive years of fiscal surpluses from 1998 to 2001, resulting in a significant decline in the debt-to-GDP ratio, despite 10-year Treasury yields remaining in the 5% to 6% range, illustrating the importance of nominal growth exceeding financing costs.
-
What signs indicate that AI-driven productivity gains are starting to affect the US economy?
💡Signs indicating that AI-driven productivity gains are starting to affect the US economy include a historically elevated direct contribution of technology investment to GDP, with information technology investment contributing 0.61 percentage points to GDP growth in Q2 2026. Additionally, JOLTS job openings have risen from 6.5 million to around 7.5 million, signaling expanding labor demand that outpaces automation, supporting resilient employment and consumption growth, which was revised up to 3.4% in Q2 2026.
-
Why does MacroMicro recommend short-term Treasuries over long-dated ones for bond exposure?
💡MacroMicro recommends short-term Treasuries over long-dated ones for bond exposure because long-dated Treasuries are likely to remain more volatile due to the US debt's maturity structure being overly concentrated at the long end. For investors needing bond exposure to reduce portfolio volatility, short-term Treasuries are considered a better choice, especially as demand for them increases and the Treasury Department shifts its issuance strategy towards shorter maturities.
-
What is the overarching investment principle when economic growth continues in an expansionary phase?
💡The overarching investment principle when economic growth continues in an expansionary phase is that equities over bonds remains the preferred allocation. This strategy is based on the expectation that sustained economic growth will drive corporate earnings and expand the tax base, supporting steady growth in tax revenue and providing fundamental support for the bond market, creating a positive fiscal cycle.
AI Supply Chain Hub + Live Outlook Track the $1T AI megatrends and the entire supply chain—all in one plan. → Claim It Before Sep 30